Washington finally put numbers on its crackdown on large institutional homebuyers this week, and the most important part of the rule is not the ban. It is the list of exceptions. When you tell the biggest buyers in single-family housing what they can no longer do, you are also telling them exactly where their money goes next.
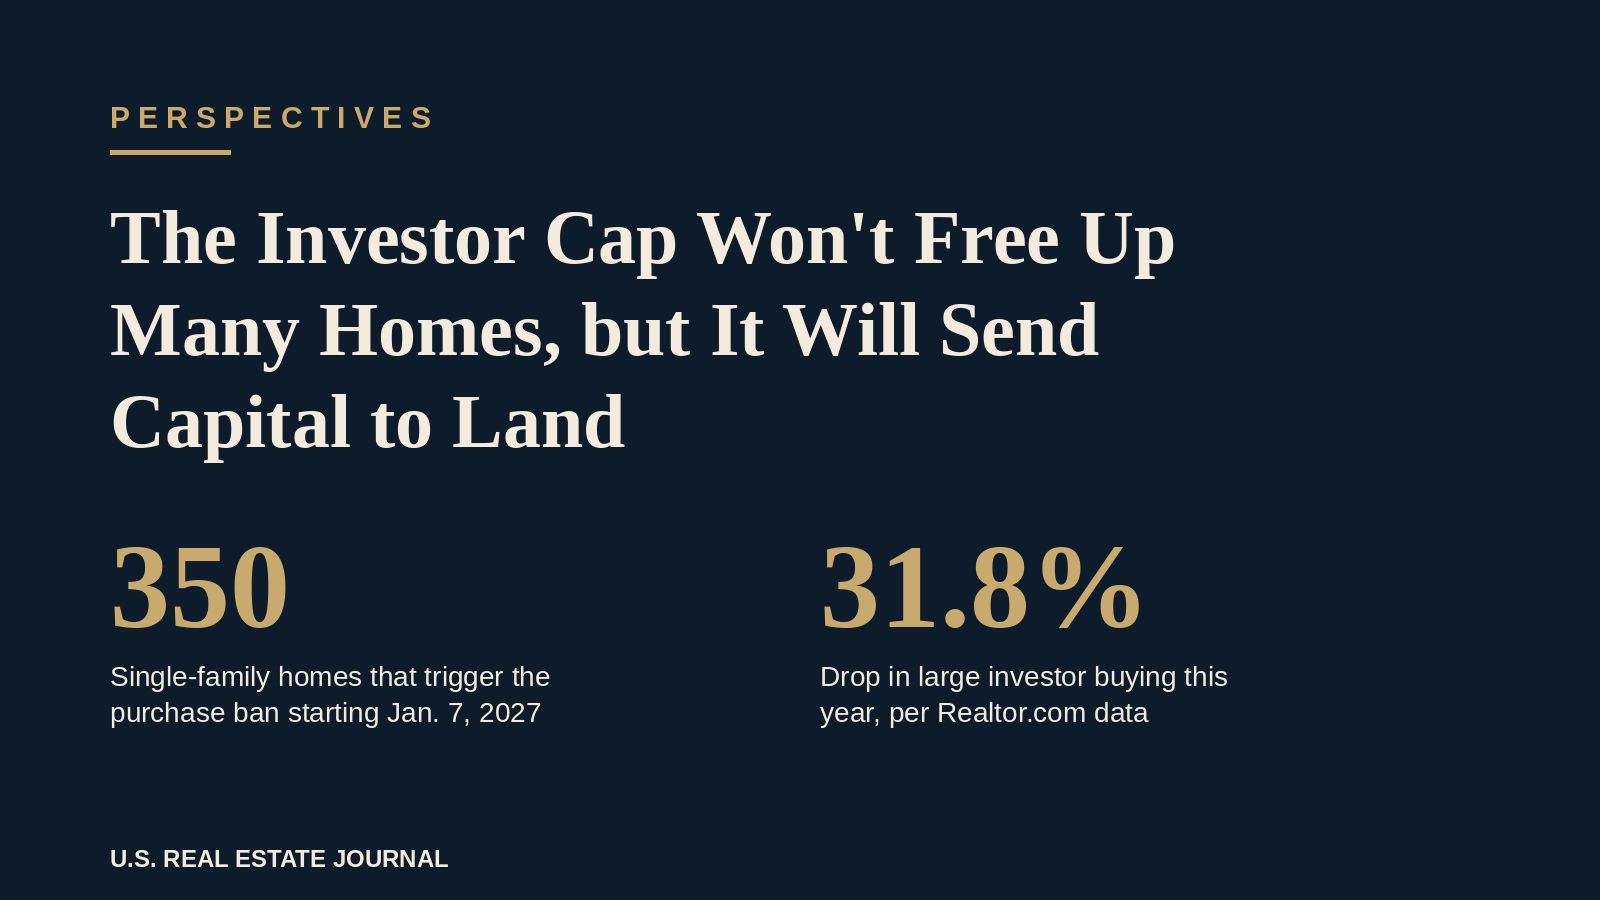
As Realtor.com reported on October 22, the Treasury Department released its proposed rule implementing the investor limits in the 21st Century Road to Housing Act, which became law in July. Investors that control 350 or more single-family homes will be barred from buying more starting January 7, 2027. Homes acquired before the law took effect on July 11 do not have to be sold. Penalties can reach $1 million or three times a property’s purchase price, and the proposal is open for 30 days of public comment.
The ban matters less than the carve-outs
Two exemptions do the real work. A build-to-rent home qualifies if it is new construction bought within 18 months of its certificate of occupancy and occupied by a renter. A renovate-to-rent home qualifies if it fails structural or core-system code elements at purchase and the investor spends at least 15% of the purchase price fixing those problems. Treasury is also asking for comment on whether to require a minimum rental period, so investors cannot build, rent briefly, and sell.
Realtor.com senior economist Hannah Jones called the package “sensible guardrails rather than a surprise,” and I agree with that read. The rule pushes large capital toward adding units and repairing distressed ones, and away from bidding against families for the existing resale house. That is the right direction. It is also a much smaller change on the ground than the political fight implied.
The reason is in the data. Realtor.com found large investor buying activity was already down 31.8% this year compared with last. Cotality notes that a January executive action restricted federal loan guarantees and securitization for sales to large institutional buyers, which raised their borrowing costs, and that institutional for-sale listings rose in the first half of 2026, many with steep price cuts. The big buyers had stepped back well before this rule arrived. Anyone expecting a wave of newly affordable starter homes in January is going to be disappointed.
Where the money goes next
Here is what I think the headline misses. Capital that was raised to buy houses does not sit still. If the resale market is closed to it, it flows through the doors left open, and the biggest door is new construction. Cotality points out that single-family build-to-rent and master-planned communities typically run 150 to 300 homes. Those projects need lots, and lots need entitlement, utilities, and roads. That is where the bottleneck has been all along.
So the practical effect of this rule is to add a well-funded bidder for entitled land in the same metros where institutional owners are already concentrated. Cotality data show some institutional buyers in Phoenix and Atlanta own more than 1,000 homes each. In those markets, land near jobs is already the scarce input, and the Southern Squeeze of insurance, property taxes, and construction costs is already pressing on margins. More money chasing the same entitled ground does not lower the price of the ground.
Closing the resale door does not shrink institutional capital. It sends that capital looking for entitled land.
For landowners and local developers holding approved sites near employment centers, that is a real opportunity. For a city council hoping the investor cap will cool its housing market, it is a reason to look hard at its own permitting and infrastructure timelines, because that is where new supply actually gets decided.
The renovation lane and turnaround markets
The second door is renovation, and I think it is underappreciated. A 15% spend requirement on homes that fail core systems is a meaningful bar. On a $150,000 house, that is at least $22,500 of real work on roofs, foundations, electrical, or plumbing. That math works best in older, lower priced housing stock, which points to the underpriced turnaround markets of the Midwest and older industrial cities. In those places the shortage is not land. It is capital willing to fix what already exists. If the rule steers even a slice of institutional money toward rehabbing neglected homes there, it could do more good than the ban itself.
It also creates a documentation burden. Someone has to prove that a house failed code at purchase and that the repair spend cleared the threshold. I expect inspection reports and construction draw records to become standard parts of every institutional acquisition file, and sloppy paperwork to become the most common way to get penalized.
What could break
The risks are real. First, the rental market that new build-to-rent homes will lease into is not tight. CRE Daily, citing RealPage, reported on October 22 that the share of stabilized apartments offering concessions fell to 14.5% in September from 17% in May, but the average discount is 11.1%, roughly 5.8 weeks of free rent and the deepest in more than 15 years. New single-family rentals compete with those deals. Underwriting a 2027 delivery off today’s asking rents, without accounting for concessions, is how sponsors get hurt.
Second, the minimum rental period is still open. If Treasury adds a long holding requirement, the exit flexibility that makes build-to-rent financeable gets narrower, and lenders will price that. Third, the 350-home line is a cliff. Operators sitting just under it face a hard ceiling on growth, which could push portfolio sales to smaller owners or creative structures that the final rule will try to close. And the K-shaped housing economy does not change. Households with equity keep winning, and renters waiting for cheaper houses to come loose from large investors are waiting on the wrong lever.
What we are watching
At Kaufman & Company, we are watching three things through the comment period and into January: whether Treasury sets a minimum rental duration, how strictly the 18-month certificate of occupancy window is enforced, and whether prices for entitled single-family lots in Phoenix, Atlanta, and the Texas metros start to move as build-to-rent capital repositions. The data will tell us more than the press releases.
If you want to follow where land and entitlement pressure is building metro by metro, the free watchlist at Land Briefing is where we track it.
Sources
- Treasury Unveils New Rules for Big Investor Homebuyers After Congress Set Limits, Realtor.com, October 22, 2026
- Capping Corporate Ownership in Single-Family Housing, Cotality, July 29, 2026
- Apartment Concessions Decline, but Discounts Remain at 15-Year Highs, CRE Daily, October 22, 2026